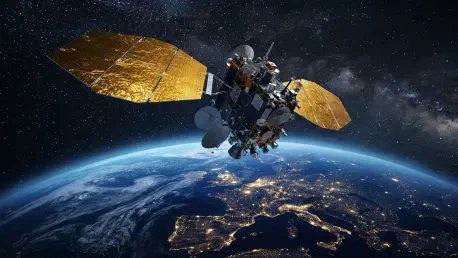
Starlink’s connectivity business is experiencing annual revenue increases of nearly 69 percent, positioning it as a significant profit driver in the space sector. This financial success mirrors a broader industry transformation where nearly 70 percent of the global mobile market is now represented by operators that have established at least one satellite partnership. These mobile network operators are no longer treating non-terrestrial networks as a niche backup; instead, they are integrating orbital capacity directly into their primary infrastructure to provide a seamless experience for a growing subscriber base. On average, these companies are managing 1.5 satellite partnerships, a calculated strategy to diversify their technological dependencies and ensure redundancy across various constellations. This trend reflects a universal industry priority to achieve 100 percent coverage, effectively erasing the boundaries between traditional cellular zones and the vast, previously unreached wilderness. By spreading investments across different orbital platforms, operators ensure that their customers stay connected regardless of terrestrial infrastructure failures or regional challenges.
Market Dominance: The Rise of Vertical Integration
SpaceX’s Starlink currently dominates the orbital landscape, controlling approximately 90 percent of the world’s deployed satellite capacity through its aggressive launch schedule. The company benefits from substantial operating leverage, using its massive subscriber revenue stream to offset the fixed costs of satellite manufacturing and deployment. This dominance has forced legacy satellite providers to rethink their business models, as the traditional boundaries between satellite providers and mobile network operators continue to blur. Starlink’s ambition to function as a standalone mobile provider in specific markets has introduced a disruptive element that challenges the conventional hierarchy of telecommunications. While regulatory hurdles regarding spectrum access remain, the sheer scale of the Starlink constellation has established a new benchmark for what is possible in the direct-to-device market. Consequently, terrestrial operators are increasingly seeking deep, multi-year partnerships to ensure they are not left behind in this rapidly evolving space race.
The industry has responded to this concentration of power with a wave of consolidation aimed at achieving a “full-stack” model that mirrors the vertical integration seen in major tech firms. Key players are seeking to own the entire value chain, from the launch vehicles and satellite manufacturing to the ground routing infrastructure and spectrum assets. Notable mergers, such as the combination of SES and Intelsat, or the strategic alignment between Eutelsat and OneWeb, reflect a desperate need for scale to compete with giants like Amazon’s Project Kuiper. These maneuvers are driven by the high financial stakes of the industry, where massive upfront capital expenditures require high-volume usage to achieve profitability. By pooling resources and spectrum, these consolidated entities hope to create enough operating leverage to survive in a market where the cost of entry is astronomical. This shift toward vertical integration is not just about survival; it is about creating a streamlined, efficient network that can deliver high-speed data to any corner of the planet without the latency issues of the past.
Strategic Imperatives: Sovereignty and Regional Infrastructure
Beyond the commercial competition, satellite technology is increasingly viewed through the lens of national sovereignty and regional security. Governments and international bodies now treat satellite constellations as critical national infrastructure, focusing heavily on where these systems are manufactured and the integrity of their supply chains. In Europe, there is a significant push for “domestic champions” to manage regional bargaining power and reduce reliance on foreign-owned technology. This focus on sovereignty has led to coordinated initiatives to manage satellite spectrum and ensure that orbital assets serve local strategic requirements rather than just global commercial interests. The shift signifies that orbital infrastructure is no longer just a business venture; it has become a central pillar of modern national and economic strategy. As nations look toward the period from 2026 to 2030, the ability to control and secure their own space-based communications will likely define their economic independence and technological resilience in an era of global uncertainty.
The utility of satellite-to-phone services varies significantly based on a region’s existing physical infrastructure and economic development. In emerging markets, particularly across Africa, satellites offer a more cost-effective solution for bridging the “coverage gap” than building thousands of terrestrial towers in rugged terrain. In these areas, the primary goal is to provide basic connectivity to people living outside the reach of a mobile signal, fostering economic growth and digital inclusion. In contrast, developed markets in Japan or Western Europe view satellite technology primarily as a “resilience layer” for emergency communications and disaster recovery. For these regions, the value of non-terrestrial networks lies in their ability to provide continuity of service when traditional networks fail during natural disasters or power outages. This regional variation ensures that satellite technology is not a one-size-fits-all solution but a flexible tool that can be adapted to meet the specific needs of diverse populations, whether they are in a dense urban center or a remote rural village.
Technical Standardization: The Path to Direct Connectivity
The transition toward seamless satellite integration has been accelerated by the rigorous efforts of global standards bodies like the 3GPP. By incorporating non-terrestrial network technologies into the latest 5G standards, the industry has paved the way for standard smartphones to connect directly to satellites without the need for specialized hardware. This development is a game-changer for the average consumer, as it removes the barrier of buying expensive, bulky satellite phones for occasional remote use. The goal is to make satellite connectivity a standard feature in the mobile ecosystem, allowing a device to switch between terrestrial towers and orbital signals automatically. While the Internet of Things and enterprise services remain meaningful revenue streams, the long-term focus has shifted toward mass-market consumer services. This standardization ensures that manufacturers can produce hardware that is compatible with a global network of satellites, fostering a competitive environment that drives down costs for users while increasing the reliability of the overall system.
Despite the rapid pace of technological advancement, industry experts acknowledge that the full realization of a global direct-to-device network is a long-term commitment. The industry is currently navigating a ten-year cycle that requires significant milestones in spectrum licensing and orbital density to be met by the end of the decade. The complexity of managing local licensing regulations across hundreds of different jurisdictions remains a major hurdle for satellite providers seeking global reach. Furthermore, the technical challenge of maintaining high-speed data links with moving satellites requires sophisticated ground-based infrastructure and advanced routing protocols. While the progress made between 2026 and 2028 has been substantial, the industry still faces a steep learning curve in optimizing network capacity for millions of simultaneous users. This gradual rollout allows operators to refine their business models and ensure that the integration of space and terrestrial assets is handled in a way that prioritizes network stability and user security above all else.
Operational Excellence: Finalizing the Global Network Vision
The telecommunications industry successfully navigated the initial complexities of orbital integration by prioritizing strategic partnerships over isolated competition. Major mobile network operators established robust protocols for handoffs between terrestrial and non-terrestrial signals, ensuring that the user experience remained consistent. These organizations moved beyond the experimental phase and implemented comprehensive training for technical teams to manage the nuances of satellite spectrum. By the midpoint of this decade, the infrastructure was finalized to support a unified global network that ignored traditional geographical boundaries. Regulators also played a critical role by standardizing the frequency allocations, which allowed for a more predictable investment environment. This period was defined by a transition from skeptical pilot programs to a fully operational reality where satellite connectivity became a standard expectation for every subscriber. The proactive stance of industry leaders ensured that the digital divide was significantly narrowed during this era of rapid transformation.
Actionable strategies for the future involved a heavy emphasis on secure supply chains and the development of sustainable orbital management practices. Companies that invested in reusable launch technology and long-lasting satellite components achieved a significant competitive advantage in terms of cost and reliability. The industry also addressed the growing concern of orbital debris by implementing strict end-of-life protocols for satellites, which preserved the space environment for future generations. These steps were essential in maintaining the public trust and the financial viability of the space-based telecommunications sector. As the focus shifted toward the next decade of progress, the lessons learned from the initial rollout of direct-to-device services provided a roadmap for further innovation in high-speed data transmission. The integration of satellite and terrestrial networks ultimately reached a state of maturity that provided a level of reliability previously thought impossible. This transformation ensured that the digital world remained accessible to everyone, regardless of their location on the planet.